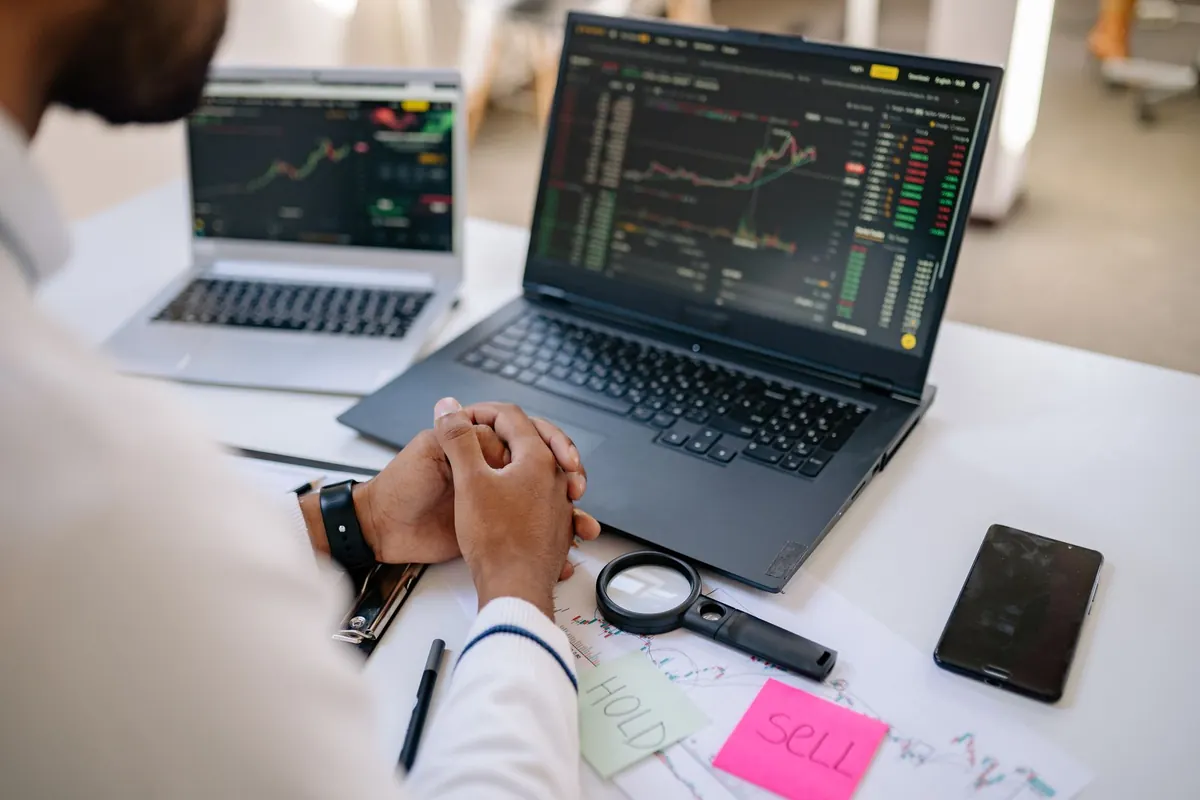
Open a chart of almost any liquid stock and you will find the same story told in miniature. A trader buys at 40.00 and puts the stop at 39.20, because a 2% loss feels civilised. Two days later the price dips to 39.05 on an ordinary afternoon, the order fills, and by the end of the week the stock is trading at 43.00. Nothing was broken. The stop did exactly what it was told. The mistake was made before the order was ever placed.
Stop-losses are simple instructions and surprisingly hard to use well. Most of the damage comes from a handful of repeated errors, and every one of them is fixable with a bit of preparation and a little honesty about your own behaviour.
The first job of a stop is not to limit your loss to a number you find tolerable. It is to get you out when the reason for the trade no longer holds. Those two distances are often very different.
Picture a stock trading near 40 that routinely travels a dollar and a half between its daily high and low. A stop 80 cents below your entry sits comfortably inside that normal movement, which means you are not being stopped out by a change of trend — you are being stopped out by the weather. Before you pick a level, pull up the last fifteen or twenty daily bars and look at how far the price actually swings. Then ask a harder question: where would price have to go before I would admit the idea is wrong? Put the stop beyond that point, not inside the noise that surrounds it.
A 1% stop is wide on a broad index fund and dangerously narrow on a small-cap stock that moves 4% before lunch. Volatility is a property of the instrument and of the moment, and your stop distance has to reflect both.
Average true range is a useful ruler here, precisely because it is boring. It tells you, roughly, how far the thing has been travelling per session lately. Expressing your stop as a multiple of that figure — say, one and a half to two times the recent range beyond your invalidation level — keeps you consistent across instruments without pretending that a software stock and a utility stock behave the same way.
The same stock also changes character. A quiet week before an earnings release and the week after it are two different markets. When volatility rises, the instinct is to keep the stop where it is and accept a higher chance of being shaken out. The better adjustment is to keep the stop where the trade logic demands and reduce your position size instead.
This is the most expensive habit in trading, and it usually arrives dressed as patience. Price drifts toward your stop, and a small internal negotiation begins. It just needs a bit more room. The level below is probably stronger anyway.
Every widened stop turns a small, planned loss into a larger, unplanned one, and it teaches you that your stops are negotiable. They are not, or they are useless. A workable rule: before you enter, write the stop down along with one sentence explaining what that level represents — the swing low that held three times, the floor of the range, the point where the trend structure breaks. The only permitted adjustment afterwards is in the direction of profit, and only at levels you marked in advance. If you feel the urge to widen, close the trade and re-enter if the setup returns. It usually does, and often at a better price.
The mirror image of the previous error is the premature move to breakeven. Trailing a stop up after a modest gain feels prudent, but it removes the room a position needs to breathe through an ordinary pullback. You end up repeatedly shaken out of trades that would have worked, paying spread and commission for the privilege.
Then there is the mental stop: the trader who knows exactly where they will exit but never places the order. This works beautifully in calm conditions and fails at precisely the moment it matters, because the decision gets made when you are least capable of making it. If your plan includes a stop, put the stop in the market, or at minimum set an alert and write the instruction down where you will see it. Check how your platform holds the order — some keep it on the broker's server, others do not — before you rely on it overnight.
Round numbers, a fixed percentage below entry, "just under the recent low" — these are positions chosen for convenience rather than meaning. They also tend to cluster, because thousands of other traders are using the same obvious reference points, and price has a habit of sweeping through clusters of orders before continuing.
A stop is an instruction, not an insurance policy. A stop-market order becomes a market order once triggered, so it fills at the next available price — which, during a gap over a weekend or in a thin market, can be well past your level. A stop-limit order protects the price but not the exit: if the market jumps over your limit, you keep a losing position you thought you had closed.
Knowing this changes how you behave around scheduled events. Some traders reduce size before an announcement rather than trusting a stop to behave in conditions where liquidity briefly disappears. Others accept a wider, calmer stop. What matters is deciding in advance which trade-off you are taking, rather than discovering it in the middle of a gap.
The stop distance and the position size are two dials on the same decision, and they should be set together. Suppose you are willing to risk 1% of a 20,000 account — 200. An entry at 50 with a stop at 47.50 risks 2.50 per share, so the position is 80 shares. If the chart says the stop belongs at 46 instead, the risk per share becomes 4.00 and the position shrinks to 50 shares. Same money at risk, different size.
Many traders work in the opposite order: they decide how many shares they want, then squeeze the stop closer to make the arithmetic fit. That is how sensible risk management quietly turns into a tight stop and a string of avoidable losses.
None of this requires more screen time, only a few minutes of order. Before entering, note the invalidation level and why it matters. Add a volatility buffer. Measure the distance and let it set your size. Choose the order type and confirm how it behaves if the market gaps. Then write the whole thing in one line you can read back to yourself when price is moving and your judgement is not at its best.
Treat the stop as part of the trade idea rather than an accessory added at the end, and most of these errors disappear on their own. Nothing here is investment advice; if you are unsure how much risk your account or your circumstances can carry, speak to a licensed professional in your jurisdiction.
Photo: Yan Krukau / Pexels
Italy's small caps absorb shocks less easily than large indices, so liquidity, family control and regulation show up...
Rate decisions move currencies through the gap between what markets priced and what central banks delivered. Here is...
A practical behavioral checklist for market corrections: why panic selling, over-concentration, skipped rebalancing...

Insights and ideas on financial markets.
