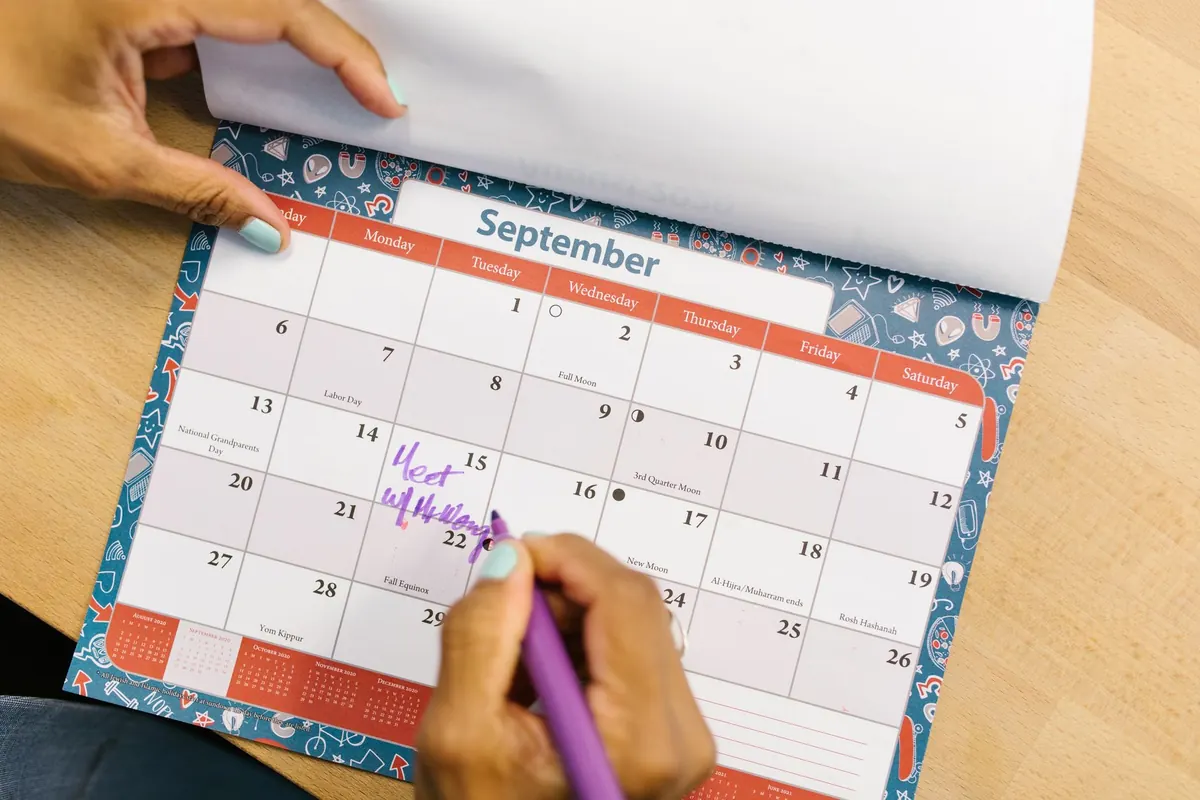
Every spring the same line makes the rounds of trading desks, newsletters and family dinner tables: sell in May and go away. It is a rhyme, not a research finding, yet it has outlived several market regimes because it compresses a genuine observation — returns are not spread evenly across the calendar — into something you can remember. That is also the problem. A rhyme is easy to repeat and hard to falsify, and the distance between "there is a mild seasonal tilt in some markets" and "move your portfolio twice a year" is where most investors do themselves damage. What follows is where the pattern comes from, what the long-run data can and cannot support, and how to hold seasonality at a sensible distance.
The phrase is usually traced to London, and to a social habit rather than a statistical discovery. The City's senior figures left for the summer, trading desks thinned out, and the market's centre of gravity shifted to the country. The full version — sell in May and go away, come back on St Leger's Day — points to a September horse race. It is a diary entry dressed up as an investment rule.
Its American cousin is the Halloween indicator: hold equities from November through April, step aside from May through October. Notice what the origin implies. The saying was built for a particular market, in a particular city, at a particular time. It was not a law of finance waiting to be discovered; it was institutional memory that later got tested. Some of that testing found a tilt. None of it found a rule.
Long-run studies of major equity indices, particularly in the US and UK, have generally found that the November-to-April stretch delivered higher average returns than May-to-October. That much is widely reported and broadly holds up over many decades. What gets lost in the retelling is everything that decides whether the finding means anything to you:
There is a second, subtler issue: statistical significance. A seasonal difference that looks clear across ninety years can look like a coin toss across ten — and ten years is roughly the horizon over which an investor has to live with a decision.
There are plausible mechanisms. Summer liquidity falls as desks empty, and thinner markets can behave differently. Tax years matter: December selling for tax losses in the US, an April year-end in the UK, both nudging flows. Earnings seasons cluster. Fund flows follow the calendar, and so does risk appetite — holidays, heat, holidays again. Older economies were agricultural, and credit tightened at harvest.
None of that is crazy. But public, documented, easy-to-trade patterns attract capital, and capital narrows them. The Monday effect is the cautionary tale: heavily documented in the 1970s and 1980s, it faded markedly after everyone knew about it. Publication is a solvent. A pattern that survives in the data may already be too small, after costs, to trade.
Acting on seasonality means getting two decisions right, not one. You have to leave at the right time and come back at the right time, and the second call is harder. The years that hurt are the ones where May-to-October rallies on thin volume while you wait on the sidelines, watching the thing you sold climb without you.
Add the practical drag. Every round trip costs commission, spread and, in many jurisdictions, tax on realised gains — a cost you may only defer, not avoid. Add the dividends you forgo while out of the market, and the compounding you interrupt. Add the behavioural cost: the discipline required to buy back in November after a strong summer is precisely the discipline most people lack. A seasonal rule that works on paper often fails in a human portfolio because the human is the weak link.
Sell in May is only the loudest voice in a crowded room. You will meet these too:
If a calendar idea crosses your path, run it through a few filters before it touches a portfolio.
The useful version of sell in May is not a trading instruction. It is a reminder that markets have rhythms, that long-run averages hide a lot of variation, and that the calendar is one input among many — valuation, diversification, costs, tax and your own time horizon all weigh more.
For most investors, the practical response is to know the pattern, note it in a written plan, and otherwise leave the portfolio alone. If you are genuinely tempted to trade it, do it with a modest tilt and a pre-agreed rule for getting back in, so the decision is made by the plan rather than by the headline. And because the tax and account consequences of any calendar-driven switch depend on your jurisdiction and circumstances, take professional advice before you act on it.
Photo: RDNE Stock project / Pexels
Italy's small caps absorb shocks less easily than large indices, so liquidity, family control and regulation show up...
Rate decisions move currencies through the gap between what markets priced and what central banks delivered. Here is...
A practical behavioral checklist for market corrections: why panic selling, over-concentration, skipped rebalancing...

Insights and ideas on financial markets.
